
Canada's Major Banks Collaborate on Tokenized CAD Deposit System
Why it matters
This initiative could redefine how banks handle deposits, enhancing competition with emerging digital payment systems.
What happened (in 30 seconds)
- On September 22, 2026, Canada's six largest banks announced a joint exploration of a shared tokenized deposit system for CAD deposits.
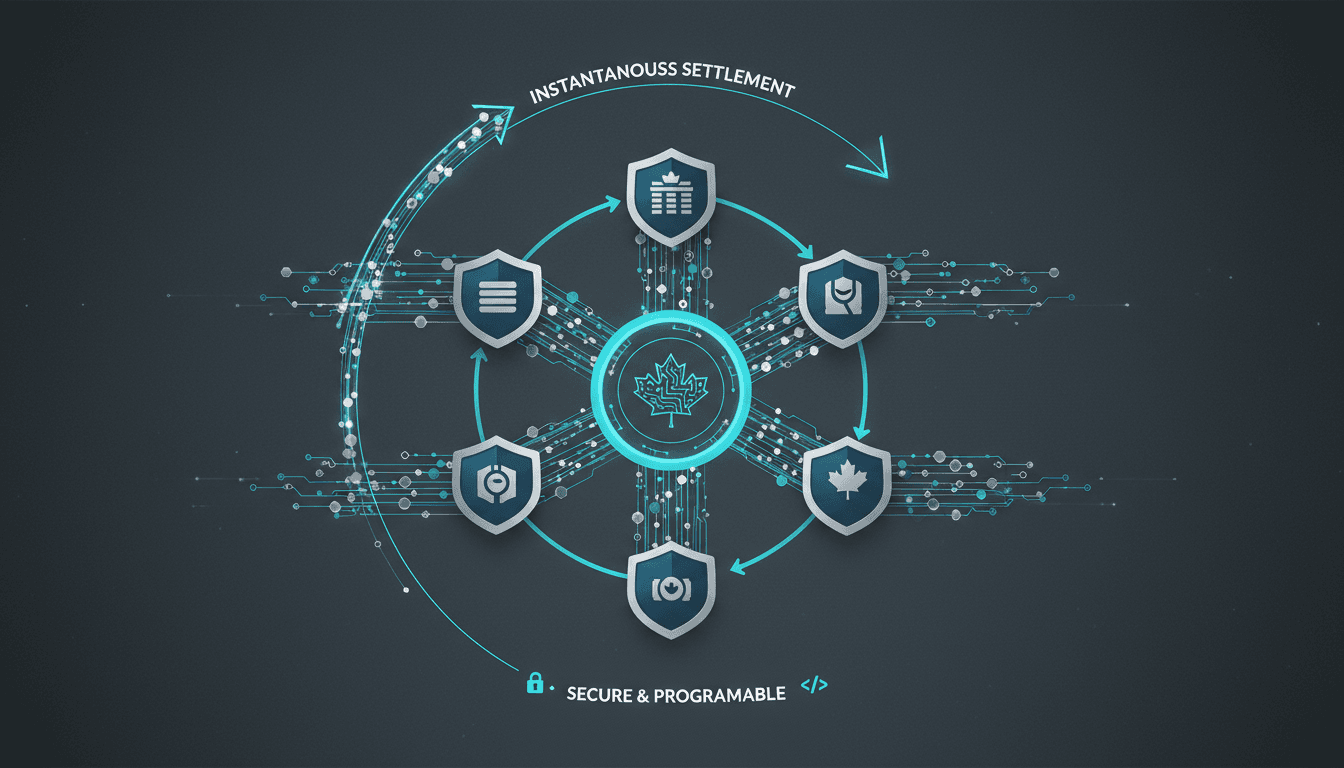
- The initiative aims to enable faster, programmable payments while maintaining regulatory oversight, distinguishing itself from stablecoins.
- The project follows recent regulatory clarifications from Canada's OSFI, building on previous tokenization experiments.
The context you actually need
- Regulatory support: The Office of the Superintendent of Financial Institutions (OSFI) clarified that tokenized deposits are legally equivalent to traditional deposits, paving the way for this initiative.
- Previous experiments: This project builds on Project Samara, which tested tokenized bond issuance and settlement, indicating a growing interest in digital asset frameworks.
- Global competition: Similar efforts are underway in the U.S., where banks are also exploring interbank tokenized deposit networks, highlighting a competitive landscape.
What's really happening
On September 22, 2026, the Big Six banks of Canada—Bank of Montreal, Canadian Imperial Bank of Commerce, National Bank of Canada, Royal Bank of Canada, Scotiabank, and TD Bank Group—announced a collaborative project to explore a shared tokenized deposit system for Canadian-dollar deposits. This initiative is significant as it aims to leverage distributed ledger technology (DLT) to facilitate interbank transfers of digital representations of bank deposits.
The primary goal of this initiative is to enable faster, programmable payments that can occur around the clock, thereby enhancing the efficiency of the banking system. Unlike stablecoins, which are often backed by reserves of fiat currency, the tokenized deposits will remain liabilities of the banks, allowing for seamless integration into existing banking frameworks without the need for separate reserve-backed assets. This distinction is crucial as it maintains regulatory oversight while promoting innovation in the banking sector.
The project is currently in its exploratory phase, with the first phase focusing on the efficient movement of tokenized CAD deposits among participating institutions. The long-term vision includes potential connections to other digital asset networks, which could further enhance the interoperability of financial systems. This collaborative approach addresses interoperability challenges that have historically hindered the adoption of digital currencies and payment systems.
The initiative follows a broader trend in the financial sector, where banks are increasingly recognizing the need to adapt to the evolving landscape of digital finance. With the rise of stablecoins and real-time payment systems, traditional banks face pressure to innovate and remain competitive. The Canadian banks' joint effort is a strategic response to these challenges, positioning them to better serve their customers and compete with emerging financial technologies.
Moreover, this initiative aligns with Canada's 2025 federal budget measures aimed at regulating stablecoins, indicating a proactive approach to digital currency governance. As the project progresses, it may expand to include additional deposit-taking institutions, further solidifying its impact on the Canadian banking landscape.
Who feels it first (and how)
- Bank customers: Individuals and businesses will benefit from faster transaction times and improved payment options.
- Financial institutions: Banks participating in the initiative will gain a competitive edge in the digital payments space.
- Regulators: The initiative may prompt regulatory bodies to adapt existing frameworks to accommodate new technologies.
What to watch next
- Interbank transfer testing: Monitor the outcomes of the first-phase interbank transfer tests, as they will indicate the feasibility of the tokenized deposit system.
- Regulatory developments: Keep an eye on any new regulations or clarifications from OSFI that could impact the initiative's progress.
- International collaborations: Watch for potential partnerships with U.S. banks, which could lead to cross-border compatibility and expanded use cases.
The initiative is in the exploratory phase, focusing on tokenized CAD deposits.
The project will expand to include more deposit-taking institutions and may connect with other digital asset networks.
The timeline for commercial launch and broader market adoption remains uncertain.
Frequently Asked Questions
- Why it matters?
- This initiative could redefine how banks handle deposits, enhancing competition with emerging digital payment systems.
- What happened (in 30 seconds)?
- On September 22, 2026, Canada's six largest banks announced a joint exploration of a shared tokenized deposit system for CAD deposits. The initiative aims to enable faster, programmable payments while maintaining regulatory oversight, distinguishing itself from stablecoins. The project follows recent regulatory clarifications from Canada's OSFI, building on previous tokenization experiments.
- What's really happening?
- On September 22, 2026, the Big Six banks of Canada—Bank of Montreal, Canadian Imperial Bank of Commerce, National Bank of Canada, Royal Bank of Canada, Scotiabank, and TD Bank Group—announced a collaborative project to explore a shared tokenized deposit system for Canadian-dollar deposits. This initiative is significant as it aims to leverage distributed ledger technology (DLT) to facilitate interbank transfers of digital representations of bank deposits. The primary goal of this initiative is
- Who feels it first (and how)?
- Bank customers: Individuals and businesses will benefit from faster transaction times and improved payment options. Financial institutions: Banks participating in the initiative will gain a competitive edge in the digital payments space. Regulators: The initiative may prompt regulatory bodies to adapt existing frameworks to accommodate new technologies.
- What to watch next?
- Interbank transfer testing: Monitor the outcomes of the first-phase interbank transfer tests, as they will indicate the feasibility of the tokenized deposit system. Regulatory developments: Keep an eye on any new regulations or clarifications from OSFI that could impact the initiative's progress. International collaborations: Watch for potential partnerships with U.S. banks, which could lead to cross-border compatibility and expanded use cases.
Real-time updates, analysis, and reports on the blockchain and cryptocurrency sectors.
"Crypto News delivers real-time updates, analysis, and reports on the blockchain and cryptocurrency sectors."
— A47 Editor
Canada’s Big Six banks explore shared tokenized deposit system
Canada's six largest banks, including TD Bank and Bank of Montreal, have initiated a joint project to test the transfer of tokenized Canadian-dollar deposits among regulated financial institutions. This effort aims to enhance the efficiency of interb...
Covers blockchain, cryptocurrency news, project analysis, and market insights.
"Cointelegraph is a leading crypto-focused media outlet known for timely news, analysis, and educational content related to blockchain and digital assets."
— A47 Editor
Canada’s six largest banks explore tokenized Canadian dollar deposits
Canada's six largest banks are exploring the implementation of tokenized Canadian dollar deposits for interbank payments, following recent regulatory clarifications on their treatment. This initiative marks a significant step towards integrating bloc...
Covers blockchain, cryptocurrency news, project analysis, and market insights.
"CoinDesk is a well-established cryptocurrency and blockchain news provider, offering comprehensive insights, market data, and industry research."
— A47 Editor
Canada's 'Big Six' banks to launch interbank tokenized deposit initiative
Canada's 'Big Six' banks are set to launch an interbank tokenized deposit initiative, focusing initially on the movement of digital commercial deposits among participating institutions. This initiative aims to enhance the efficiency of interbank tran...