
SEC Issues FAQs Clarifying Crypto Asset Investment Contract Analysis
Why it matters
This guidance clarifies how issuer promises affect the classification of crypto assets, potentially reshaping market dynamics and investor expectations.
What happened (in 30 seconds)
- On September 25, 2026, the SEC's Division of Corporation Finance issued nine FAQs regarding crypto asset issuers and investment contracts.
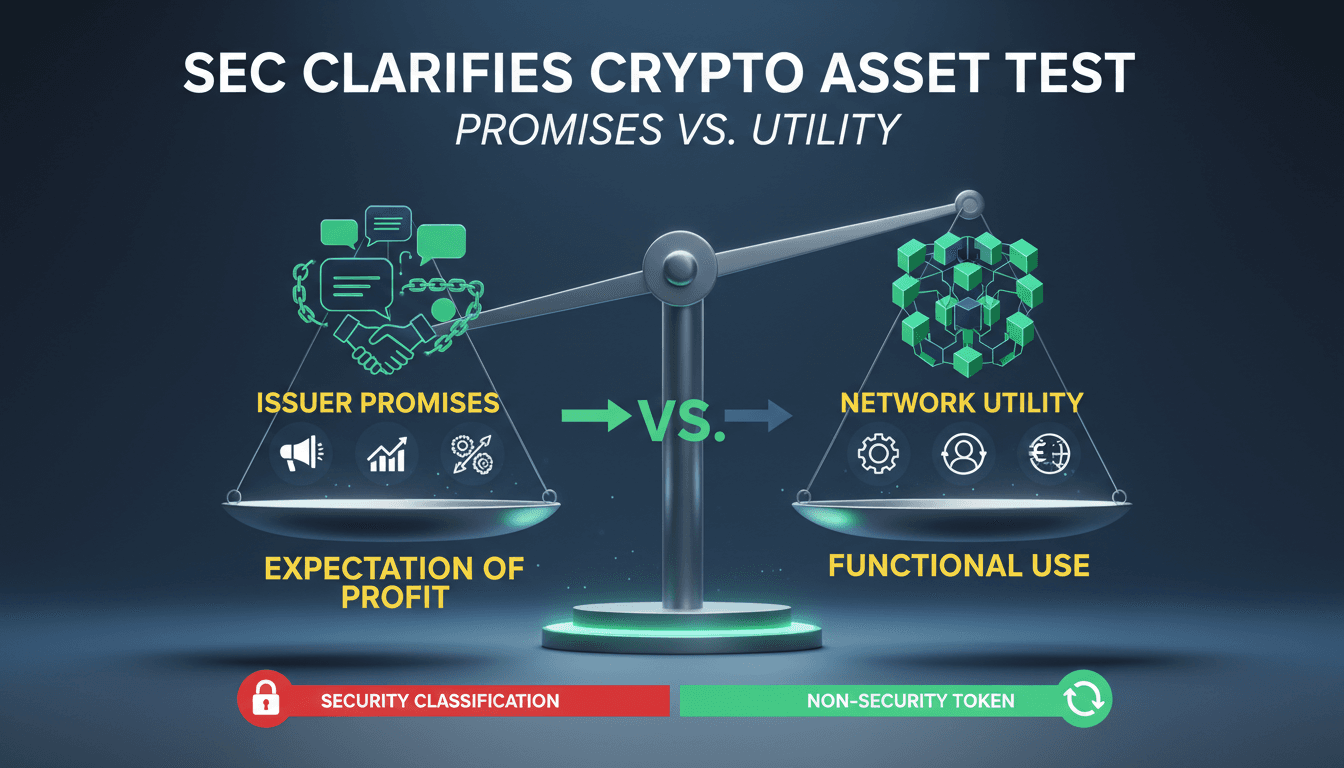
- The guidance emphasizes that buyer expectations of profits from issuer promises can classify non-security tokens as investment contracts.
- No immediate market reactions have been documented following the release, as the guidance holds no legal force.
The context you actually need
- The SEC's March 2026 release previously classified most crypto assets as non-securities but allowed for investment contracts based on issuer promises.
- The FAQs distinguish between general network utility descriptions and specific promises that could create profit expectations for buyers.
- Existing legal frameworks, particularly the Howey test, continue to inform the SEC's approach to crypto asset regulation.
What's really happening
The SEC's recent FAQs provide critical interpretive guidance on how representations made by crypto asset issuers can influence whether their tokens are classified as securities under U.S. law. This guidance is particularly relevant in the context of the Howey test, which assesses whether an investment contract exists based on the expectations of profit derived from the efforts of others.
The SEC's staff clarifies that not all communications from issuers will trigger securities treatment. For instance, general descriptions of a network's utility are less likely to create investment contract expectations compared to specific promises of future work that could generate profits. This distinction is crucial for both issuers and investors, as it determines the regulatory landscape in which these assets operate.
The FAQs also address various aspects of crypto asset operations, such as buybacks and staking receipts. Buyback announcements, for example, are evaluated based on the stage of the network and how they are presented. If framed as creating yield, they may lead to different interpretations under the law. Similarly, staking receipts are generally viewed as digital tools unless they confer additional rights or the issuer retains control over the underlying asset.
Moreover, the guidance indicates that merely operating a secondary market does not automatically classify a platform as a promoter under Rule 405. This nuance is significant for trading platforms and exchanges, as it delineates their responsibilities and potential liabilities in the crypto space.
The SEC's emphasis on the issuer's own representations when measuring the completion of promised functionalities or decentralization is another critical point. This means that if an issuer claims certain capabilities or levels of decentralization, they are held accountable to those claims, regardless of whether they transfer obligations to another party.
Overall, the SEC's guidance aims to provide clarity in a rapidly evolving market, helping issuers navigate compliance while protecting investors from misleading representations. However, it is essential to note that these staff views do not carry legal force or Commission approval, leaving room for interpretation and potential future adjustments.
Who feels it first (and how)
- Crypto asset issuers: They must carefully craft their communications to avoid inadvertently classifying their tokens as securities.
- Investors: Those purchasing crypto assets will need to assess the promises made by issuers to understand their investment's regulatory status.
- Trading platforms: They may need to adjust their operations and marketing strategies based on the new guidance to avoid regulatory pitfalls.
What to watch next
- Market reactions: Watch for any shifts in trading volumes or asset valuations as the market digests the implications of the SEC's guidance.
- Regulatory responses: Keep an eye on how other regulatory bodies, both domestic and international, respond to the SEC's clarifications.
- Legal challenges: Monitor for any legal disputes arising from the interpretation of these FAQs, as they could set important precedents.
The SEC's guidance clarifies the treatment of crypto assets based on issuer promises.
Issuers will adjust their marketing and operational strategies to align with the new guidance.
The long-term impact on market dynamics and investor behavior remains to be seen.
Frequently Asked Questions
- Why it matters?
- This guidance clarifies how issuer promises affect the classification of crypto assets, potentially reshaping market dynamics and investor expectations.
- What happened (in 30 seconds)?
- On September 25, 2026, the SEC's Division of Corporation Finance issued nine FAQs regarding crypto asset issuers and investment contracts. The guidance emphasizes that buyer expectations of profits from issuer promises can classify non-security tokens as investment contracts. No immediate market reactions have been documented following the release, as the guidance holds no legal force.
- What's really happening?
- The SEC's recent FAQs provide critical interpretive guidance on how representations made by crypto asset issuers can influence whether their tokens are classified as securities under U.S. law. This guidance is particularly relevant in the context of the Howey test, which assesses whether an investment contract exists based on the expectations of profit derived from the efforts of others. The SEC's staff clarifies that not all communications from issuers will trigger securities treatment. For i
- Who feels it first (and how)?
- Crypto asset issuers: They must carefully craft their communications to avoid inadvertently classifying their tokens as securities. Investors: Those purchasing crypto assets will need to assess the promises made by issuers to understand their investment's regulatory status. Trading platforms: They may need to adjust their operations and marketing strategies based on the new guidance to avoid regulatory pitfalls.
- What to watch next?
- Market reactions: Watch for any shifts in trading volumes or asset valuations as the market digests the implications of the SEC's guidance. Regulatory responses: Keep an eye on how other regulatory bodies, both domestic and international, respond to the SEC's clarifications. Legal challenges: Monitor for any legal disputes arising from the interpretation of these FAQs, as they could set important precedents.
Covers Bitcoin plus altcoin news, market updates, and educational resources.
"Bitcoin.com provides news, market data, and guides focused on Bitcoin and the wider crypto industry."
— A47 Editor
SEC Staff Clarifies How Crypto Promises Affect Securities Treatment
The U.S. Securities and Exchange Commission (SEC) has clarified how the promises made by cryptocurrency issuers can influence the classification of their tokens as securities. This clarification is part of ongoing efforts to establish a regulatory fr...
Bitcoin news, technical analysis, and forecasts across crypto markets.
"NewsBTC covers Bitcoin news, technical analysis, and forecasts across crypto markets and major blockchain projects."
— A47 Editor
SEC Clarifies When Crypto Buybacks And Network Upgrades Can Raise Securities Questions
The U.S. Securities and Exchange Commission (SEC) has released new FAQs clarifying how federal securities laws may apply to crypto-asset buybacks, network upgrades, and secondary-market activities. This guidance indicates that buybacks may be conside...
Real-time updates, analysis, and reports on the blockchain and cryptocurrency sectors.
"Crypto News delivers real-time updates, analysis, and reports on the blockchain and cryptocurrency sectors."
— A47 Editor
SEC staff clarifies when staking tokens may avoid securities rules
The U.S. Securities and Exchange Commission (SEC) staff has clarified the conditions under which staking receipt tokens may be classified as digital tools rather than securities, addressing key issues related to wrapped assets, token buybacks, and fu...