
Marvell Agrees to All-Stock Acquisition of Lumentum at 4.5 Shares per Lumentum Share as Mizuho Trims Price Target to $1,132
Why it matters
The consolidation reveals that securing physical optical interconnects for advanced data centers requires chipmakers to accept prolonged balance-sheet dilution and complex multi-year integration timelines.
What happened (in 30 seconds)
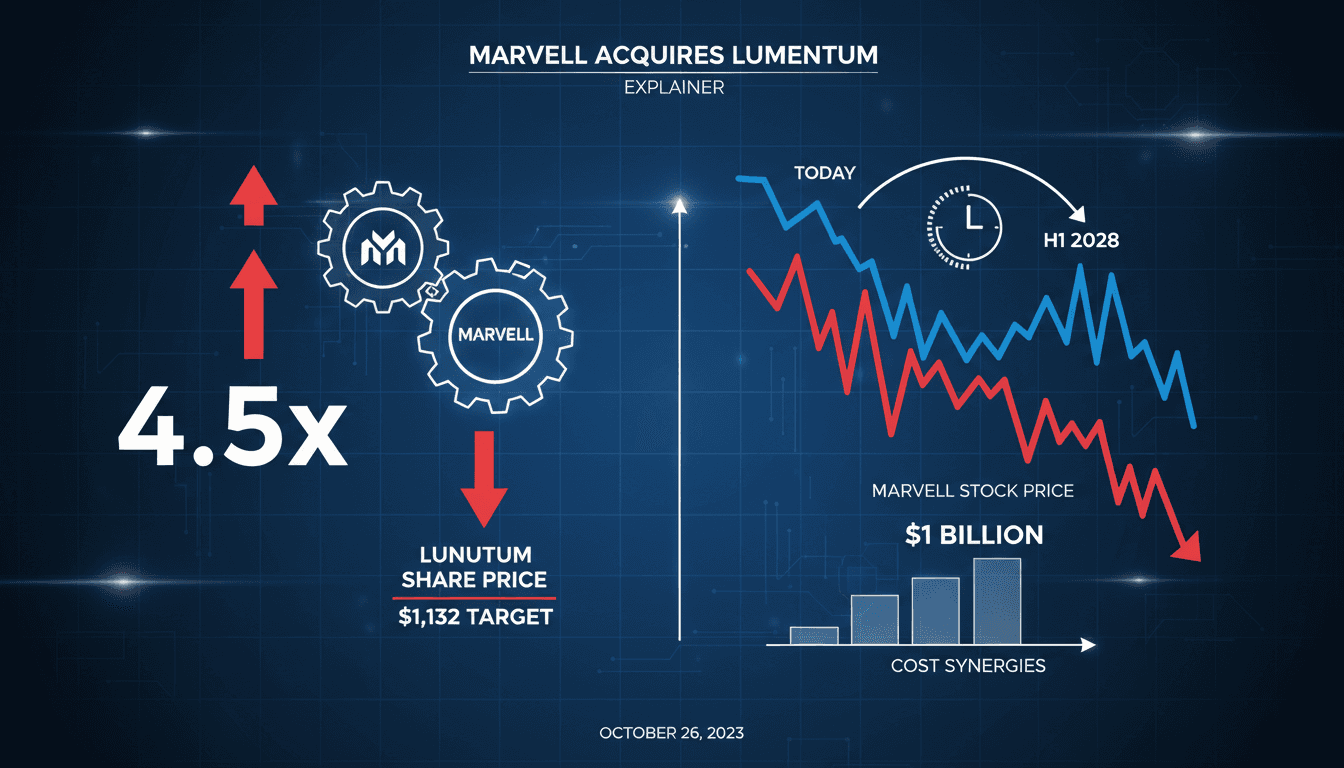
- Marvell agreed to acquire Lumentum in an all-stock transaction structured at a fixed exchange ratio of 4.5 Marvell shares per Lumentum share, implying an acquisition valuation of roughly $1,132 per share.
- Lumentum delivered earnings outperformance, posting September quarter revenue of $1.26 billion alongside earnings per share of $4.57, while issuing December quarter financial guidance that exceeded consensus expectations.
- Both equities experienced immediate sell-offs on November 2, 2026, with Lumentum shares dropping approximately 18.6% and Marvell retreating 12.7% as Mizuho lowered its Lumentum price target to $1,132 from $1,140 while retaining an Outperform rating.
The context you actually need
- Optical interconnect demand is surging, driven by strict data center requirements for high-speed transmission where 800G and 1.6T transceivers face constrained component supply.
- Lumentum entered the transaction from operational strength, having generated 317% stock returns over the prior year supported by 83% revenue growth as hyperscalers accelerated hardware purchasing.
- Wall Street analysts diverged sharply on the structure, with Raymond James upgrading Lumentum to Strong Buy while Stifel downgraded the stock to Hold, Bank of America cut Marvell to Neutral, and B. Riley reduced its target on Marvell.
What's really happening
The economic logic behind Marvell’s buyout of Lumentum highlights a structural shift in how semiconductor architects solve compute bottlenecks: processing silicon can no longer scale independently of optical transport layers. Modern artificial intelligence training clusters rely on moving vast quantities of data between graphics processing units, network interface cards, and switches. As internal data center pipelines advance toward 800G and 1.6T throughput, standard copper connections face severe physical limitations regarding heat dissipation and signal degradation. Integrating electro-absorption modulated laser (EML) transceivers and optical circuit switches directly with networking silicon resolves these physical transport bottlenecks.
However, the capital markets responded to this strategic step with notable skepticism. The core tension stems directly from the transaction mechanics. By structuring an all-stock acquisition at a fixed exchange ratio of 4.5 Marvell shares for each Lumentum share, Marvell absorbs substantial equity dilution today to capture $1 billion in projected long-term cost synergies that will not materialize until after the deal closes in the first half of 2028. This extended timeline—spanning roughly 18 months—exposes both companies to cyclical market swings, antitrust evaluations, and operational integration risks before a single dollar of joint cash flow is realized.
The trading floor reaction on November 2, 2026, illustrates the immediate cost of this structural bet. Despite Lumentum reporting $1.26 billion in quarterly revenue, $4.57 in earnings per share, and forward guidance exceeding consensus estimates, its equity tumbled 18.6%. Marvell fell 12.7%. Because the transaction relies on a fixed exchange ratio, Lumentum's immediate market value became locked to Marvell’s trading trajectory. Mizuho analyst Vijay Rakesh mirrored this mathematical reality: he trimmed Lumentum’s price target from $1,140 down to $1,132—precisely matching the implied acquisition parity—even while maintaining an Outperform rating based on gross margin expansion and tight 800G and 1.6T transceiver supply.
The transaction forces institutional investors to weigh long-term vertical integration against intermediate operational risk. Lumentum shareholders exchange high-margin standalone revenue growth—underpinned by 83% year-over-year gains—for equity in a larger, combined networking conglomerate subject to sector contraction risks and multi-year restructuring. Marvell secures essential optical intellectual property and manufacturing lines, but it must manage complex supply constraints and optical circuit switch production ramps across multiple product generations before the merger formally completes.
Who feels it first (and how)
- Data center infrastructure procurement leads: Face locked-in vendor consolidation across high-speed optical transceivers and switching silicon, altering their long-term component sourcing leverage.
- Marvell and Lumentum institutional equity holders: Bear immediate capital drawdowns following double-digit share declines, while navigating an 18-month fixed-ratio equity peg.
- Optical transceiver component suppliers: Must navigate persistent factory allocation pressures for 800G and 1.6T EML hardware while customer organizations prepare for post-merger supply chain realignments.
- Technology sector equity research analysts: Forced to re-evaluate standalone valuation multiples against prolonged deal overhangs, as evidenced by simultaneous downgrades and upgrades across major brokerages.
What to watch next
- Transceiver production delivery metrics: Tracking quarterly delivery volumes for 800G and 1.6T EML components will verify whether underlying gross margin expansion targets remain achievable amid ongoing supply constraints.
- Regulatory filing progress: Monitoring antitrust review milestones across global jurisdictions will signal whether the projected first-half 2028 closing schedule remains realistic.
- Customer qualification cycles: Observing whether hyperscalers accelerate or pause deployments of Lumentum’s optical circuit switches prior to formal integration with Marvell’s silicon platforms will clarify customer retention.
Marvell announced an all-stock acquisition of Lumentum at a ratio of 4.5 shares per Lumentum share; Mizuho adjusted its target to $1,132; the companies target $1 billion in cost synergies with a targeted closing date in the first half of 2028.
The stock price correlation between Marvell and Lumentum will remain tightly tethered around the 4.5 exchange multiple, capping independent valuation expansion for Lumentum.
Whether regulatory reviews will impose divestitures on specialized optical assets, or if the prolonged closure timeline will prompt enterprise customers to diversify transceiver orders to competing optical specialists.
Frequently Asked Questions
- Why it matters?
- The consolidation reveals that securing physical optical interconnects for advanced data centers requires chipmakers to accept prolonged balance-sheet dilution and complex multi-year integration timelines.
- What happened (in 30 seconds)?
- Marvell agreed to acquire Lumentum in an all-stock transaction structured at a fixed exchange ratio of 4.5 Marvell shares per Lumentum share, implying an acquisition valuation of roughly $1,132 per share. Lumentum delivered earnings outperformance, posting September quarter revenue of $1.26 billion alongside earnings per share of $4.57, while issuing December quarter financial guidance that exceeded consensus expectations. Both equities experienced immediate sell-offs on November 2, 2026, with L
- What's really happening?
- The economic logic behind Marvell’s buyout of Lumentum highlights a structural shift in how semiconductor architects solve compute bottlenecks: processing silicon can no longer scale independently of optical transport layers. Modern artificial intelligence training clusters rely on moving vast quantities of data between graphics processing units, network interface cards, and switches. As internal data center pipelines advance toward 800G and 1.6T throughput, standard copper connections face seve
- Who feels it first (and how)?
- Data center infrastructure procurement leads: Face locked-in vendor consolidation across high-speed optical transceivers and switching silicon, altering their long-term component sourcing leverage. Marvell and Lumentum institutional equity holders: Bear immediate capital drawdowns following double-digit share declines, while navigating an 18-month fixed-ratio equity peg. Optical transceiver component suppliers: Must navigate persistent factory allocation pressures for 800G and 1.6T EML hardware
- What to watch next?
- Transceiver production delivery metrics: Tracking quarterly delivery volumes for 800G and 1.6T EML components will verify whether underlying gross margin expansion targets remain achievable amid ongoing supply constraints. Regulatory filing progress: Monitoring antitrust review milestones across global jurisdictions will signal whether the projected first-half 2028 closing schedule remains realistic. Customer qualification cycles: Observing whether hyperscalers accelerate or pause deployments of
Brokerage upgrades/downgrades, price-target changes, and fresh coverage that move single names and sectors.
"Handy for tracking sentiment shifts from the sell side and consensus drift."
— A47 Editor
Mizuho lowers Lumentum stock price target on Marvell acquisition
Mizuho lowered its stock price target on Lumentum following Marvell's agreed acquisition of the data centre component maker, a move reported by Investing.com on November 2, 2026. The base report frames the adjustment as negative for Lumentum's outloo...
Global business headlines with AI angles.
"General business outlet that frequently covers AI."
— A47 Editor
Marvell Announces $115 Billion Acquisition of Optical Components Maker Lumentum to in Effort to Upgrade AI Speed
Marvell Technology has announced an acquisition of optical components maker Lumentum in a deal valued at about $115 billion, with the companies expecting the transaction to close in the first half of 2028, subject to shareholder and regulatory approv...
Editor-curated FT homepage stories spanning markets, business, world, and opinion.
"The Financial Times is a globally respected business publication with a centrist/center-left tone and strong markets focus."
— A47 Editor
Marvell to buy data centre component maker Lumentum in $115bn AI bet
Marvell Technology has agreed to acquire data centre component maker Lumentum in an all-stock deal that the Financial Times reports is valued at roughly $115bn, with both companies describing the combination as creating a leader in AI connectivity.
Global markets, investing, and macroeconomics from a premier financial newsroom.
"Bloomberg is respected for in-depth financial reporting and data-driven analysis."
— A47 Editor
Marvell’s AI Megadeal Hands Wall Street Multiple M&A Milestones
Marvell Technology Inc. is taking over data center laser maker Lumentum Holdings Inc. in a $115 billion deal, a transaction that Bloomberg reports will move Wall Street past several mergers and acquisitions milestones in a year already marked by mega...
U.S. business news, corporate developments, and economy.
"The Wall Street Journal is respected for deep financial and economic reporting with a center-right editorial perspective."
— A47 Editor
Chip Maker Marvell Agrees to Buy Lumentum in $80 Billion Deal
Chip maker Marvell has agreed to buy Lumentum in a deal valued at about $80 billion, a transaction The Wall Street Journal reports would combine two fast-growing suppliers of technology used in artificial intelligence.