
Anthropic Q3 2026 Results Show Decelerating Revenue Growth and Rising Compute Costs Ahead of IPO Valuation Talks
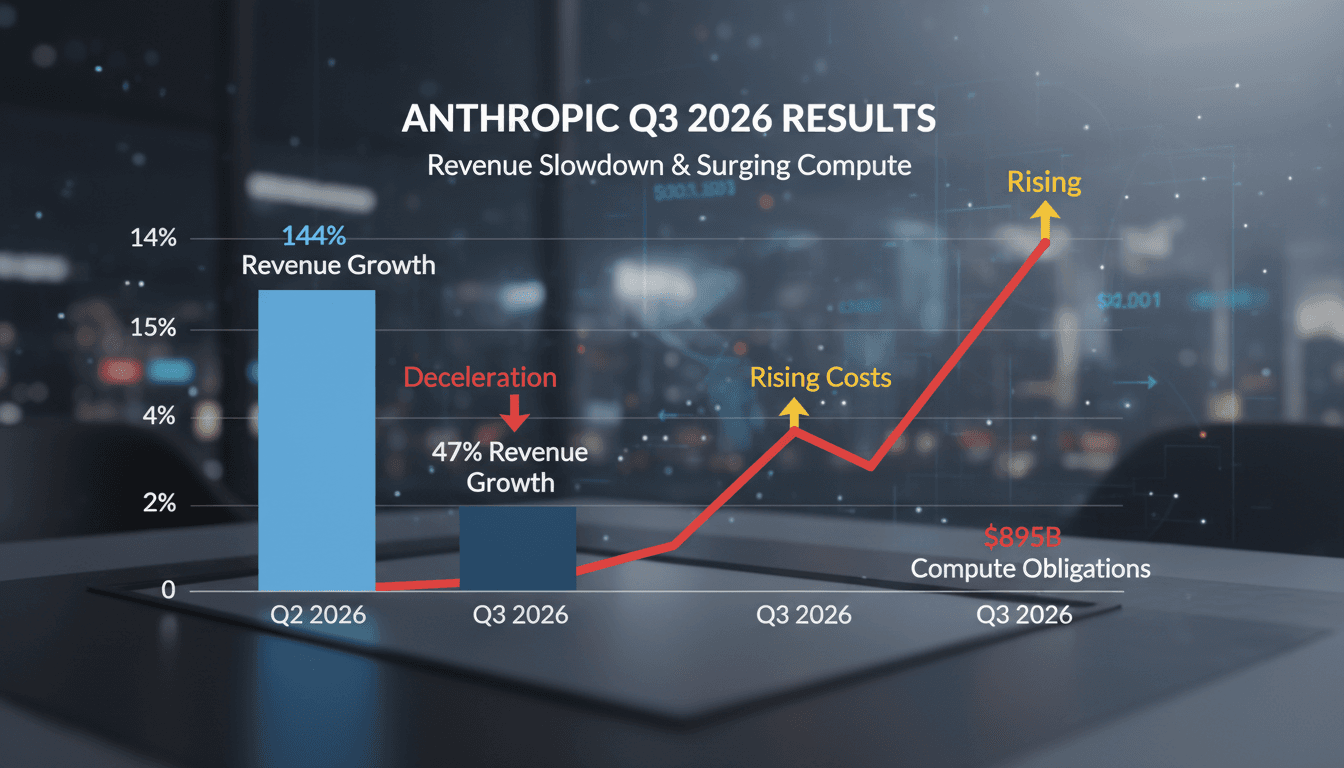
Decelerating revenue alongside soaring compute liabilities forces enterprise buyers and market allocators to prepare for tighter AI software pricing and lower multiple benchmarks across the tech ecosystem.
Why it matters
The divergence between Anthropic's slowing revenue growth and escalating infrastructure commitments marks the transition of frontier artificial intelligence from an unconstrained expansion phase into a disciplined, balance-sheet-constrained capital cycle.
What happened (in 30 seconds)
- Top-line expansion slowed: Anthropic reported third-quarter 2026 revenue of approximately $16.96 billion, representing a 47% sequential rise that dropped sharply from the 144% quarter-over-quarter growth logged in the prior period.
- Compute outlays eroded margins: Infrastructure and processing expenses surged 77% sequentially to $9.9 billion, weighed down by $5 billion in spot-capacity acquisitions that pushed adjusted operating margins down to 15% from 19%.
- Allocators pushed back on targets: Institutional investors voiced hesitation over the company's planned $1.5 trillion to $2 trillion public valuation range, pushing discussions toward the conservative floor as long-term compute commitments crossed $895 billion.
The context you actually need
- Historical IPO precedents rarely support this pricing: Data compiled by Jay Ritter examining 4,110 initial public offerings between 1980 and 2024 revealed that only 14 issuers traded at comparable price-to-sales ratios, with that cohort collectively lagging baseline market performance over the long term.
- Independent intrinsic valuations remain firm: NYU Stern valuation specialist Aswath Damodaran held his pre-quarter benchmark at $1.475 trillion, indicating that underlying free cash flow trajectories do not yet justify the premium upper bound sought by underwriters.
- Fixed obligations dwarf trailing liquidity: Anthropic amended its S-1 registration statement to incorporate operational numbers that show future compute obligations exceeding $895 billion, placing systemic focus on durable unit economics over raw revenue growth.
What's really happening
The underlying friction behind Anthropic’s public filing comes down to capital efficiency versus infrastructure lock-in. For multiple fiscal cycles, capital markets permitted generative AI pioneers to operate without traditional cost controls under the premise that gross software margins would emerge once scale arrived. Anthropic's third-quarter disclosures suggest the inverse: scaling state-of-the-art models introduces compounding compute expenses that outstrip near-term revenue gains.
Sequential revenue expansion normalized from 144% to 47%. While generating roughly $17 billion in a single quarter reflects substantial market adoption for the Claude platform, maintaining that top line demanded $9.9 billion in compute and operational infrastructure across the same three-month window. Crucially, $5 billion of those expenditures derived from short-term spot capacity acquisitions—the most expensive mechanism for running high-density training and inference workloads. The direct outcome was an adjusted operating margin compression of 400 basis points, landing at 15%.
This cost profile changes how asset allocators evaluate the business. In typical enterprise software models, marginal distribution costs decline toward zero as customer acquisition compounds. In foundation model deployment, serving the customer requires persistent, heavy graphics processing hardware. When enterprise clients scale usage, the provider's cost of goods sold rises in tandem unless baseline inference efficiencies increase dramatically.
Consequently, the target valuation range of $1.5 trillion to $2 trillion implies that market participants must pay between $43 and $57 for every dollar of trailing twelve-month revenue. Institutional investors, including Impax Asset Management and Theory Ventures, point out that tech issuers commanding these multiples historically underperform standard market benchmarks. With long-term infrastructure commitments established at more than $895 billion, Anthropic is essentially committed to high fixed operational expenditure for years to come.
Underwriters face a pricing standoff. Setting the initial listing near the $2 trillion ceiling requires assuming sequential growth will reaccelerate while server costs diminish—assumptions contradicted by the third-quarter numbers. Pricing at or below $1.5 trillion protects public market buyers but resets valuation multiples lower across the entire generative AI sector.
Who feels it first (and how)
- Institutional asset allocators: Portfolio managers recalibrating late-stage venture books face repricing pressures across artificial intelligence equity portfolios if public multiples settle at the lower boundary of historical norms.
- Enterprise software buyers: Corporate procurement teams negotiating enterprise AI tooling may encounter stiffer platform pricing and diminished vendor subsidies as frontier labs focus on shoring up operating margins.
- Regional sovereign wealth funds: Global investment vehicles in financial centers like Dubai, which deploy institutional balance sheets into cross-border tech infrastructure, face broader market volatility that demands rigorous validation of compute-to-revenue ratios.
- Cloud infrastructure and hardware vendors: Advanced server providers and capacity brokers encounter changing buyer behavior, as frontier model companies seek to curb reliance on high-cost spot capacity in favor of strict margin defense.
What to watch next
- The finalized roadshow price band: The amended valuation range submitted prior to the November 2026 listing date will reveal whether investment banks successfully defended the $2 trillion target or succumbed to institutional pressure at $1.5 trillion.
- Spot capacity outlays in Q4 disclosures: Monitoring whether short-term compute purchases remain elevated above the third quarter's $5 billion mark will clarify if margin deterioration is structural or merely a temporary supply bottleneck.
- Enterprise contract structures: Shifts toward multi-year minimum volume commitments or revised API rate limits will indicate how aggressively foundation model labs are pushing infrastructure costs onto enterprise customers.
Anthropic generated approximately $16.96 billion in third-quarter 2026 revenue (up 47% sequentially), incurred $9.9 billion in compute costs, maintains over $895 billion in computing commitments, and has targeted an initial public offering valuation between $1.5 trillion and $2 trillion.
Underwriters will price the offering near the lower threshold of $1.5 trillion to accommodate institutional pushback regarding historical price-to-sales multiple underperformance and margin degradation.
Whether upcoming algorithmic improvements will lower inference costs sufficiently to restore operating margins above 19% without forcing steep price increases across commercial products.
Frequently Asked Questions
- Why it matters?
- The divergence between Anthropic's slowing revenue growth and escalating infrastructure commitments marks the transition of frontier artificial intelligence from an unconstrained expansion phase into a disciplined, balance-sheet-constrained capital cycle.
- What happened (in 30 seconds)?
- Top-line expansion slowed: Anthropic reported third-quarter 2026 revenue of approximately $16.96 billion, representing a 47% sequential rise that dropped sharply from the 144% quarter-over-quarter growth logged in the prior period. Compute outlays eroded margins: Infrastructure and processing expenses surged 77% sequentially to $9.9 billion, weighed down by $5 billion in spot-capacity acquisitions that pushed adjusted operating margins down to 15% from 19%. Allocators pushed back on targets: Ins
- What's really happening?
- The underlying friction behind Anthropic’s public filing comes down to capital efficiency versus infrastructure lock-in. For multiple fiscal cycles, capital markets permitted generative AI pioneers to operate without traditional cost controls under the premise that gross software margins would emerge once scale arrived. Anthropic's third-quarter disclosures suggest the inverse: scaling state-of-the-art models introduces compounding compute expenses that outstrip near-term revenue gains. Sequen
- Who feels it first (and how)?
- Institutional asset allocators: Portfolio managers recalibrating late-stage venture books face repricing pressures across artificial intelligence equity portfolios if public multiples settle at the lower boundary of historical norms. Enterprise software buyers: Corporate procurement teams negotiating enterprise AI tooling may encounter stiffer platform pricing and diminished vendor subsidies as frontier labs focus on shoring up operating margins. Regional sovereign wealth funds: Global investmen
- What to watch next?
- The finalized roadshow price band: The amended valuation range submitted prior to the November 2026 listing date will reveal whether investment banks successfully defended the $2 trillion target or succumbed to institutional pressure at $1.5 trillion. Spot capacity outlays in Q4 disclosures: Monitoring whether short-term compute purchases remain elevated above the third quarter's $5 billion mark will clarify if margin deterioration is structural or merely a temporary supply bottleneck. Enterpris
Corporate leadership, finance, technology, and market trends.
"Fortune covers financial trends, leadership, and innovation with a pragmatic editorial approach."
— A47 Editor
Anthropic’s third-quarter results mean IPO math and history are not on its side, analysts say
Analysts say Anthropic's third-quarter results weaken the case for investors earning above-market returns from its planned IPO, even if it prices well below the $1.5 trillion to $2 trillion valuation it reportedly seeks.
AI news with an enterprise and cloud focus.
"Covers AI in the context of data infrastructure, cloud, and enterprise stacks."
— A47 Editor
Anthropic’s quarterly revenue jumps to $17B, losses grow ahead of IPO
Anthropic PBC published an updated S-1 filing for its upcoming public offering that included third-quarter financial results, showing $17 billion in revenue for the three months ended Sept. 30, more than eleven times higher than the same period a yea...
Tech business coverage, major deals, product launches, and Silicon Valley trends.
"WSJ’s tech section offers authoritative reporting on the intersection of technology and business, including exclusive industry analysis."
— A47 Editor
Anthropic Investors Push for Cautious Valuation Closer to $1.5 Trillion
Institutional investors planning to buy shares in Anthropic's proposed IPO are pressing for a cautious valuation nearer to $1.5 trillion, following a selloff in tech stocks that has heightened concern about entering the offering at peak pricing.
Markets desk coverage, trading insights, and investor updates.
"WSJ’s markets reporting provides in-depth analysis and context for investors."
— A47 Editor
Anthropic Investors Push for Cautious Valuation Closer to $1.5 Trillion
Investors in Anthropic's planned initial public offering are pressing for a cautious valuation nearer to $1.5 trillion, following a selloff in tech stocks that has heightened concern among institutional buyers, according to The Wall Street Journal.
Curated tech headlines including AI stories.
"Influential aggregator surfacing the day’s top tech/AI links."
— A47 Editor
Sources: institutional investors told Anthropic that its IPO valuation should be around $1.5T to $1.6T, down from estimates of $2T, citing a tech stock selloff (Wall Street Journal)
Institutional investors planning to buy shares in Anthropic's IPO have told the company its valuation should be around $1.5 trillion to $1.6 trillion, down from earlier estimates of $2 trillion, citing a selloff in tech stocks, according to sources c...
AI/ML research and technology news.
"Sister site to Phys.org focusing on tech research."
— A47 Editor
Anthropic says revenue surged 1,100% ahead of IPO
Anthropic reported a more than 1,100% surge in quarterly revenue and nearly $900 billion in spending commitments as it approaches its planned Nasdaq listing under the ticker "ANT" later this month, according to figures disclosed in its public S-1 reg...
Global markets, investing, and macroeconomics from a premier financial newsroom.
"Bloomberg is respected for in-depth financial reporting and data-driven analysis."
— A47 Editor
Anthropic IPO Explained: S-1 Filing, Nasdaq Listing and Key Risks
Anthropic, the San Francisco-based AI company behind the Claude chatbot, is preparing one of the most closely watched initial public offerings in recent memory, with a filing with the US Securities and Exchange Commission and a planned Nasdaq listing...
Business and tech news excluding paywalled content.
"High-volume business/tech outlet with frequent AI coverage."
— A47 Editor
Anthropic's amended IPO paperwork reveals soaring Q3 revenue and a stunning compute bill
Anthropic's amended S-1 filing with the U.S. Securities and Exchange Commission shows third-quarter revenue jumped to nearly $17 billion, while its compute and infrastructure commitments reached $895 billion, as the AI company advances toward a plann...