
Australia Proposes Draft Legislation for OECD Crypto-Asset Reporting Framework
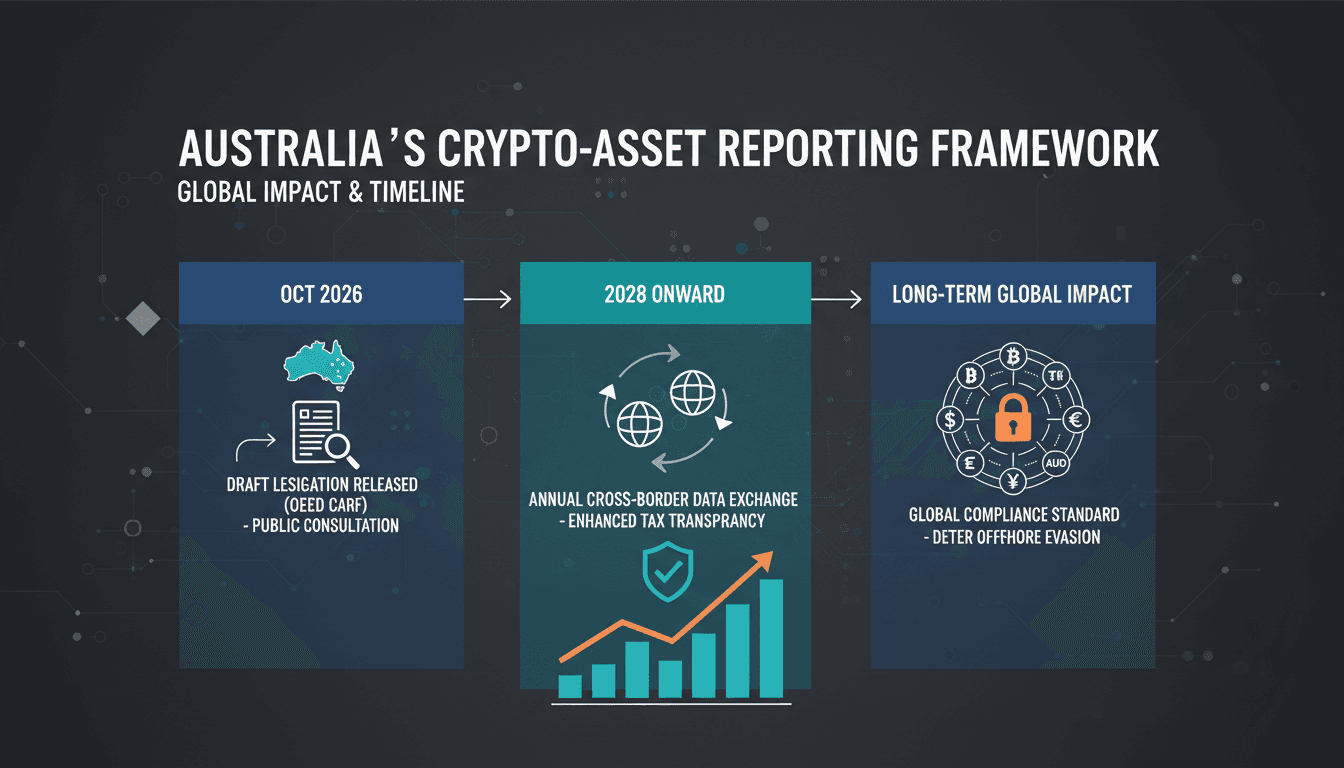
If you engage with cryptocurrencies in Australia, expect increased scrutiny and reporting requirements starting in 2028.
Why it matters
This legislation aims to enhance tax transparency and combat offshore tax evasion, impacting how crypto transactions are reported globally.
What happened (in 30 seconds)
- On October 15, 2026, the Australian Treasury released draft legislation to implement the OECD’s Crypto-Asset Reporting Framework (CARF).
- The proposal requires crypto service providers to report transactions involving Australian residents and facilitates annual cross-border data exchanges starting in 2028.
- Public consultation on the draft legislation runs until October 28, 2026, before potential parliamentary introduction.
The context you actually need
- The OECD developed CARF to address challenges in tracking crypto assets held or traded through foreign providers, with 77 jurisdictions committed as of September 2026.
- Australia's commitment to CARF was made in November 2023, with implementation plans confirmed in the 2025–26 Mid-Year Economic and Fiscal Outlook.
- The framework updates existing Common Reporting Standards, aligning Australia with global tax transparency efforts without introducing new tax rates on cryptocurrencies.
What's really happening
The Australian Treasury's draft legislation marks a significant step in the global effort to regulate cryptocurrency transactions and enhance tax compliance. By adopting the OECD's Crypto-Asset Reporting Framework (CARF), Australia aims to create a structured approach to monitor and report crypto transactions involving its residents. This move is part of a broader initiative to deter tax evasion and ensure that crypto assets are treated similarly to traditional financial assets in terms of reporting obligations.
Under the proposed framework, crypto service providers will be required to collect and report detailed user identification and transaction data. This includes exchanges between cryptocurrencies and fiat currencies, as well as transfers between different crypto assets. The Australian Taxation Office (ATO) will receive this data, allowing for better tracking of tax obligations and compliance among Australian residents.
The first international data exchanges under CARF are scheduled for 2028, which means that crypto transactions involving Australian residents will be scrutinized not only domestically but also in the context of global tax compliance. This is particularly relevant as 77 jurisdictions have committed to CARF, indicating a growing consensus on the need for standardized reporting in the crypto space.
The draft legislation is currently open for public consultation until October 28, 2026, allowing stakeholders to provide feedback that may influence the final version before it is introduced to Parliament. This process is crucial as it ensures that the concerns of various parties, including crypto service providers and users, are considered in the legislative framework.
While the proposal is still in draft form, it signals a clear intention from the Australian government to align its tax reporting practices with international standards. This alignment is expected to enhance tax transparency and reduce the potential for tax evasion through offshore crypto transactions. However, it also raises questions about the implications for users and service providers, particularly regarding compliance costs and the operational challenges of adapting to new reporting requirements.
Who feels it first (and how)
- Crypto service providers: They will need to implement new systems for tracking and reporting transactions.
- Australian residents: Individuals engaging in crypto transactions will face increased scrutiny and potential tax obligations.
- International exchanges: Companies operating across borders may need to adapt to new compliance requirements when dealing with Australian residents.
What to watch next
- Public consultation outcomes: Feedback from stakeholders could lead to significant revisions in the draft legislation before it is finalized.
- International participation: Watch for updates on how other jurisdictions, including the UAE, respond to CARF and whether they will implement similar frameworks.
- Market reactions: Monitor how crypto markets react to the proposed legislation and any shifts in trading behavior among Australian residents.
The draft legislation requires crypto service providers to report transactions involving Australian residents.
The first international data exchanges under CARF will occur in 2028, impacting global crypto reporting standards.
The full extent of compliance costs and operational challenges for crypto service providers remains to be seen.
Frequently Asked Questions
- Why it matters?
- This legislation aims to enhance tax transparency and combat offshore tax evasion, impacting how crypto transactions are reported globally.
- What happened (in 30 seconds)?
- On October 15, 2026, the Australian Treasury released draft legislation to implement the OECD’s Crypto-Asset Reporting Framework (CARF). The proposal requires crypto service providers to report transactions involving Australian residents and facilitates annual cross-border data exchanges starting in 2028. Public consultation on the draft legislation runs until October 28, 2026, before potential parliamentary introduction.
- What's really happening?
- The Australian Treasury's draft legislation marks a significant step in the global effort to regulate cryptocurrency transactions and enhance tax compliance. By adopting the OECD's Crypto-Asset Reporting Framework (CARF), Australia aims to create a structured approach to monitor and report crypto transactions involving its residents. This move is part of a broader initiative to deter tax evasion and ensure that crypto assets are treated similarly to traditional financial assets in terms of repor
- Who feels it first (and how)?
- Crypto service providers: They will need to implement new systems for tracking and reporting transactions. Australian residents: Individuals engaging in crypto transactions will face increased scrutiny and potential tax obligations. International exchanges: Companies operating across borders may need to adapt to new compliance requirements when dealing with Australian residents.
- What to watch next?
- Public consultation outcomes: Feedback from stakeholders could lead to significant revisions in the draft legislation before it is finalized. International participation: Watch for updates on how other jurisdictions, including the UAE, respond to CARF and whether they will implement similar frameworks. Market reactions: Monitor how crypto markets react to the proposed legislation and any shifts in trading behavior among Australian residents.
Real-time updates, analysis, and reports on the blockchain and cryptocurrency sectors.
"Crypto News delivers real-time updates, analysis, and reports on the blockchain and cryptocurrency sectors."
— A47 Editor
Australia moves to share crypto tax data globally by 2028
Australia has proposed new crypto tax reporting rules under the OECD framework, with public feedback due by October 28, and plans to exchange data globally by 2028. This initiative aligns Australia with 77 jurisdictions committed to the OECD's Crypto...
Covers blockchain, cryptocurrency news, project analysis, and market insights.
"Cointelegraph is a leading crypto-focused media outlet known for timely news, analysis, and educational content related to blockchain and digital assets."
— A47 Editor
Australia releases draft bill to adopt OECD crypto tax reporting framework
Australia has released a draft bill to adopt the OECD's Crypto-Asset Reporting Framework (CARF), joining 77 jurisdictions committed to this international standard, with the first exchanges of crypto tax data expected in 2028.
English-language digital publication covering business, politics, technology, and current affairs.
"The Arabian Post mixes original and syndicated-style coverage with a broad regional and global business-news orientation."
— A47 Editor
Australia proposes mandatory crypto tax reporting from 2027
Australia has proposed draft legislation that mandates cryptocurrency platforms to report transactions involving Australian residents to tax authorities starting in July 2027. The Treasury announced this proposal on October 15, 2026, and is currently...